Bracket Orders and OCO: Plan the Stop and Target Before Entry
Last saved:
Executive Summary
- ✦A bracket links an entry with a protective stop and target, while OCO logic normally cancels the unused exit.
- ✦Calculate position size from the entry-to-stop distance before sending the order.
- ✦Stop-market orders prioritise exit but can slip; stop-limit orders control price but may not fill.
- ✦Verify quantities after partial fills and learn whether the orders are held by the exchange, broker server or local platform.
Bracket Orders and OCO: Plan the Stop and Target Before Entry
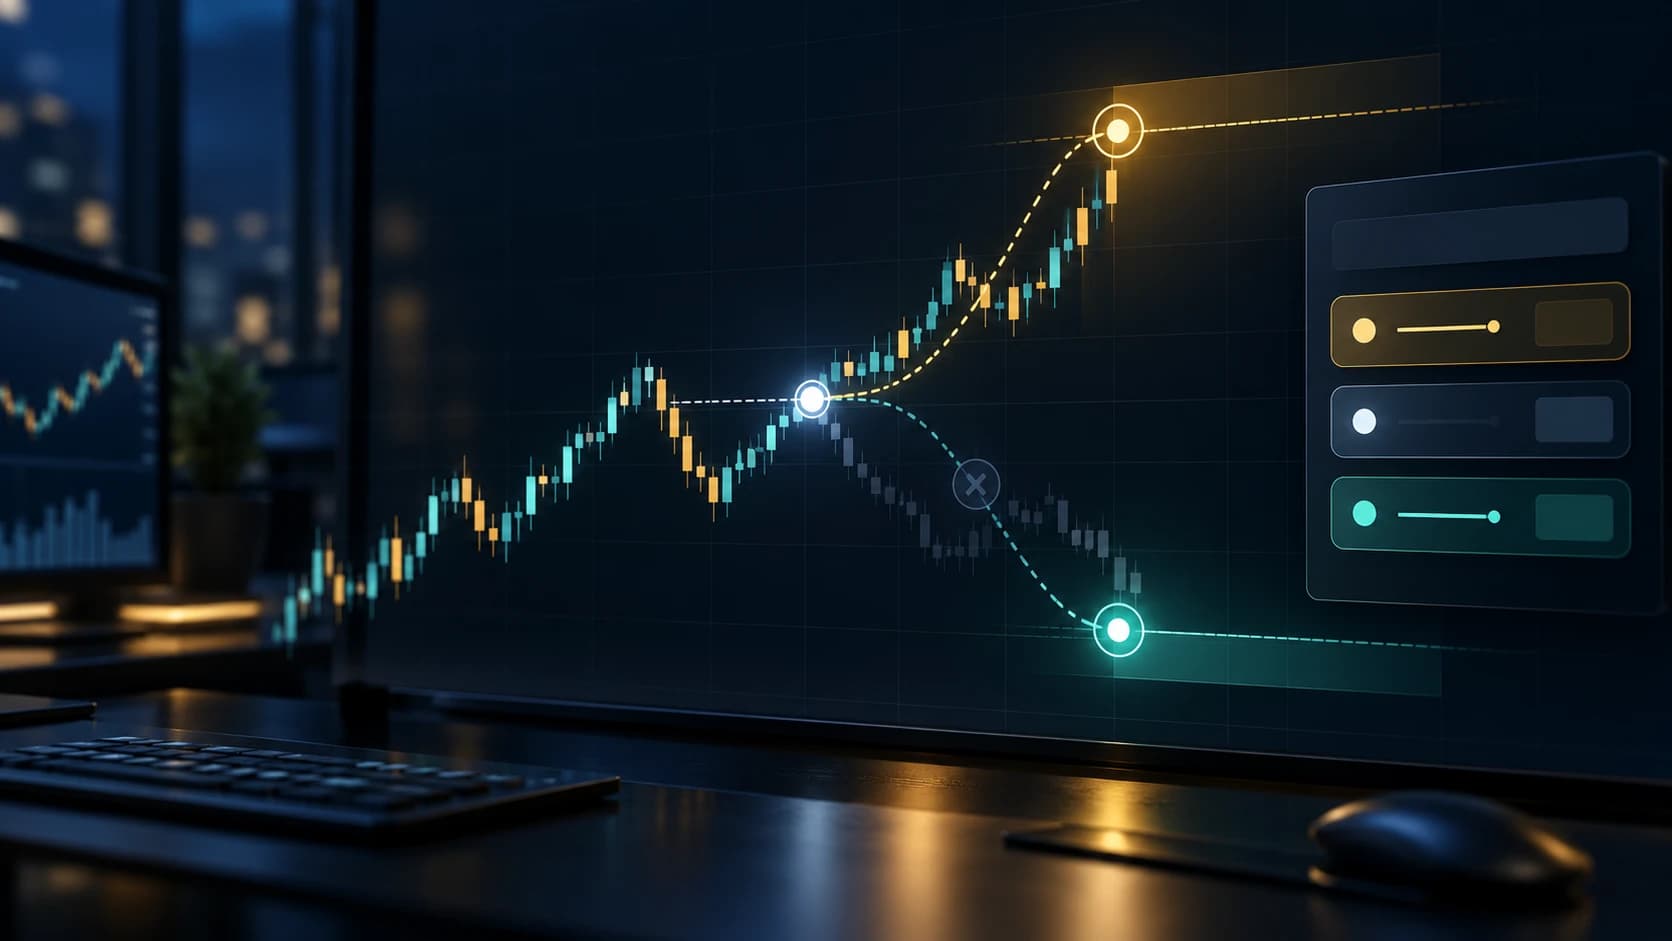
A trade plan is incomplete if it defines only the entry. Price can move quickly after an order fills, and a trader who decides the stop and target under pressure may take more risk than intended. A bracket order can attach two planned exits to an entry: a protective stop and a profit-taking order. When one exit fills, the other is normally cancelled through one-cancels-the-other, or OCO, logic.
The tool can improve execution discipline, but it does not guarantee the planned exit price. Gaps, slippage, partial fills, rejected orders and platform rules still matter.
Learning objective
By the end, you should be able to describe how a bracket order works, choose suitable stop and target order types, calculate quantity from the stop distance, handle partial fills and verify whether the protection is held by the exchange, broker or trading platform.
This lesson builds on market, limit and stop orders, position sizing and stop placement.
What a bracket order contains
A typical long bracket has three related instructions:
- Entry order: buy the instrument if the entry condition is met.
- Protective stop: sell if price reaches the invalidation area.
- Profit target: sell if price reaches the planned objective.
The stop and target form the OCO pair. If the target executes, the stop should be cancelled. If the stop executes, the target should be cancelled. A short bracket reverses the directions: the entry sells short, while both exits buy back the position.
The word “should” matters. Exact behaviour depends on the broker, venue and product. Some platforms hold the OCO relationship on their own server. Some send native orders to an exchange. Others simulate one or both exits locally. Read the order documentation before assuming protection remains active during a lost connection or platform outage.
Step 1: define invalidation before the entry
The stop belongs where the trade idea is no longer valid, subject to liquidity and execution risk. It should not be chosen only because a fixed cash amount feels comfortable.
For a long breakout, invalidation might be a confirmed return below the broken level. For a range trade, it might be beyond the opposite side of the structure. Volatility can help judge whether normal price noise is likely to reach the proposed stop.
Once the entry and stop are defined, calculate the risk per unit:
Risk per unit = planned entry − stop price
Then use the account risk budget to estimate quantity:
Quantity = risk budget ÷ risk per unit
Adjust for contract multipliers, currency conversion, commission, slippage and the possibility of a gap through the stop. Percentage-risk figures are examples for testing, not universal rules.
Step 2: choose the entry order deliberately
A bracket can begin with different entry types:
- Limit entry: controls the maximum purchase price or minimum short-sale price, but may not fill.
- Stop entry: activates after price reaches a trigger, useful for confirmation, but may fill with slippage.
- Market entry: prioritises execution, but the fill price can differ from the quote.
The attached exits should use the actual filled quantity and, where relevant, the actual average fill price. If a 1,000-share limit order fills only 300 shares, an exit for all 1,000 could create an unintended short position unless the platform automatically resizes the bracket.
Step 3: understand stop-market versus stop-limit protection
A stop-market order becomes a market order when triggered. It prioritises getting out, but it does not guarantee price. In a gap or thin market, the fill can be materially worse than the stop level.
A stop-limit order becomes a limit order. It controls the worst acceptable price, but it may remain unfilled while the market continues through the limit. That makes it unsuitable when certainty of exit is more important than price control.
Neither removes risk. The correct choice depends on the instrument, liquidity, holding period and failure mode the trader can tolerate.
Step 4: set a target that fits the thesis
The target should reflect market structure, expected move and the strategy's tested distribution. It should not be placed only to manufacture an attractive reward-to-risk ratio.
A target just beyond strong resistance may be less realistic than one placed before it. A trend-following strategy may use a trailing exit instead of a fixed target. A mean-reversion strategy may aim for the range midpoint or opposite boundary. The bracket is an execution container; it does not create an edge.
Worked example: size first, then attach the exits
Assume a hypothetical trader plans a long trade with:
- intended entry: £50.20;
- invalidation and stop trigger: £49.40;
- risk budget: £160;
- initial target: £52.20.
Risk per share is:
£50.20 − £49.40 = £0.80
Ignoring costs for the first calculation:
£160 ÷ £0.80 = 200 shares
The gross target distance is £2.00 per share, or 2.5 times the planned £0.80 price risk. That ratio is not a forecast of success. The trader must still account for commission, spread, stop slippage and the chance that the entry fills at a different price.
Suppose only 120 shares fill at an average £50.18. The live stop and target should each cover 120 shares, not the original 200. If another 80 shares fill later, the platform must add them to the exits or create a separate bracket. The trader should verify this rather than assume it happened.
If price gaps from £49.55 to £49.10, a stop-market order triggered at £49.40 may fill near £49.10 or worse. The realised loss can exceed the £160 plan. Position sizing should leave room for that execution risk.
Step 5: test partial exits and quantity changes
Complexity rises when a trader scales out. If half the position closes at the first target, the stop quantity must fall by the same amount. Otherwise, a later stop could sell more than remains open.
Before using a bracket live, test in a simulator or very small size:
- partial entry fills;
- partial target fills;
- manual reduction of the position;
- replacing the stop price;
- cancelled entry orders;
- platform disconnection;
- trading halts and reopening gaps;
- what happens outside regular trading hours.
Confirm the final state in the broker's order and position screens. A chart marker alone may not prove that an order is working at the venue.
Common mistakes
- Sending an entry before calculating the stop distance and quantity.
- Assuming the target and stop are OCO when they are independent orders.
- Using a stop-limit order without accepting the risk of no fill.
- Leaving exit quantity unchanged after a partial fill or manual reduction.
- Moving the stop farther away to avoid taking the planned loss.
- Treating a displayed stop price as a guaranteed execution price.
- Assuming simulated orders remain active when the device or connection fails.
- Forgetting that some products use different sessions, triggers or price references.
Practical checklist
Before submitting a bracket, verify:
- Is the trade thesis and invalidation written down?
- Is size calculated from the stop distance and total risk budget?
- Which price triggers the stop: last, bid, offer, mark or index?
- Is the stop market or stop-limit, and why?
- Are the exits truly linked by OCO logic?
- Where are the orders held: exchange, broker server or local platform?
- Will quantities resize after partial fills?
- Are the exits active outside regular trading hours?
- What is the plan for gaps, halts or a rejected order?
The Money Man view
A bracket order is most valuable as a process tool. It forces the trader to connect entry, invalidation, quantity and exit before market pressure rises. Its main weakness is false confidence: the presence of lines on a chart does not prove a guaranteed exit.
Treat the bracket as automation of a tested plan, then verify every working order after entry and every quantity change. Good order linkage reduces operational mistakes, while sensible sizing limits the damage when execution is worse than planned.
Educational information only, not personalised investment or financial advice. Trading involves loss risk, and stop or OCO orders cannot guarantee execution or price. Order behaviour varies by broker, exchange, product and market conditions; test the workflow and read the relevant provider documentation before trading.