Monte Carlo Analysis: How Trade Order Changes Drawdown Risk
Last saved:
Executive Summary
- ✦The same trades in a different order can create a very different drawdown.
- ✦Choose a resampling method that reflects dependence and market regimes.
- ✦Reproduce the live sizing rule and include realistic costs.
- ✦Treat percentiles as conditional estimates, not guaranteed limits.
Learning objective: use Monte Carlo resampling to estimate how the order of wins and losses can change drawdown, losing streaks and account paths even when the strategy's average result is unchanged.
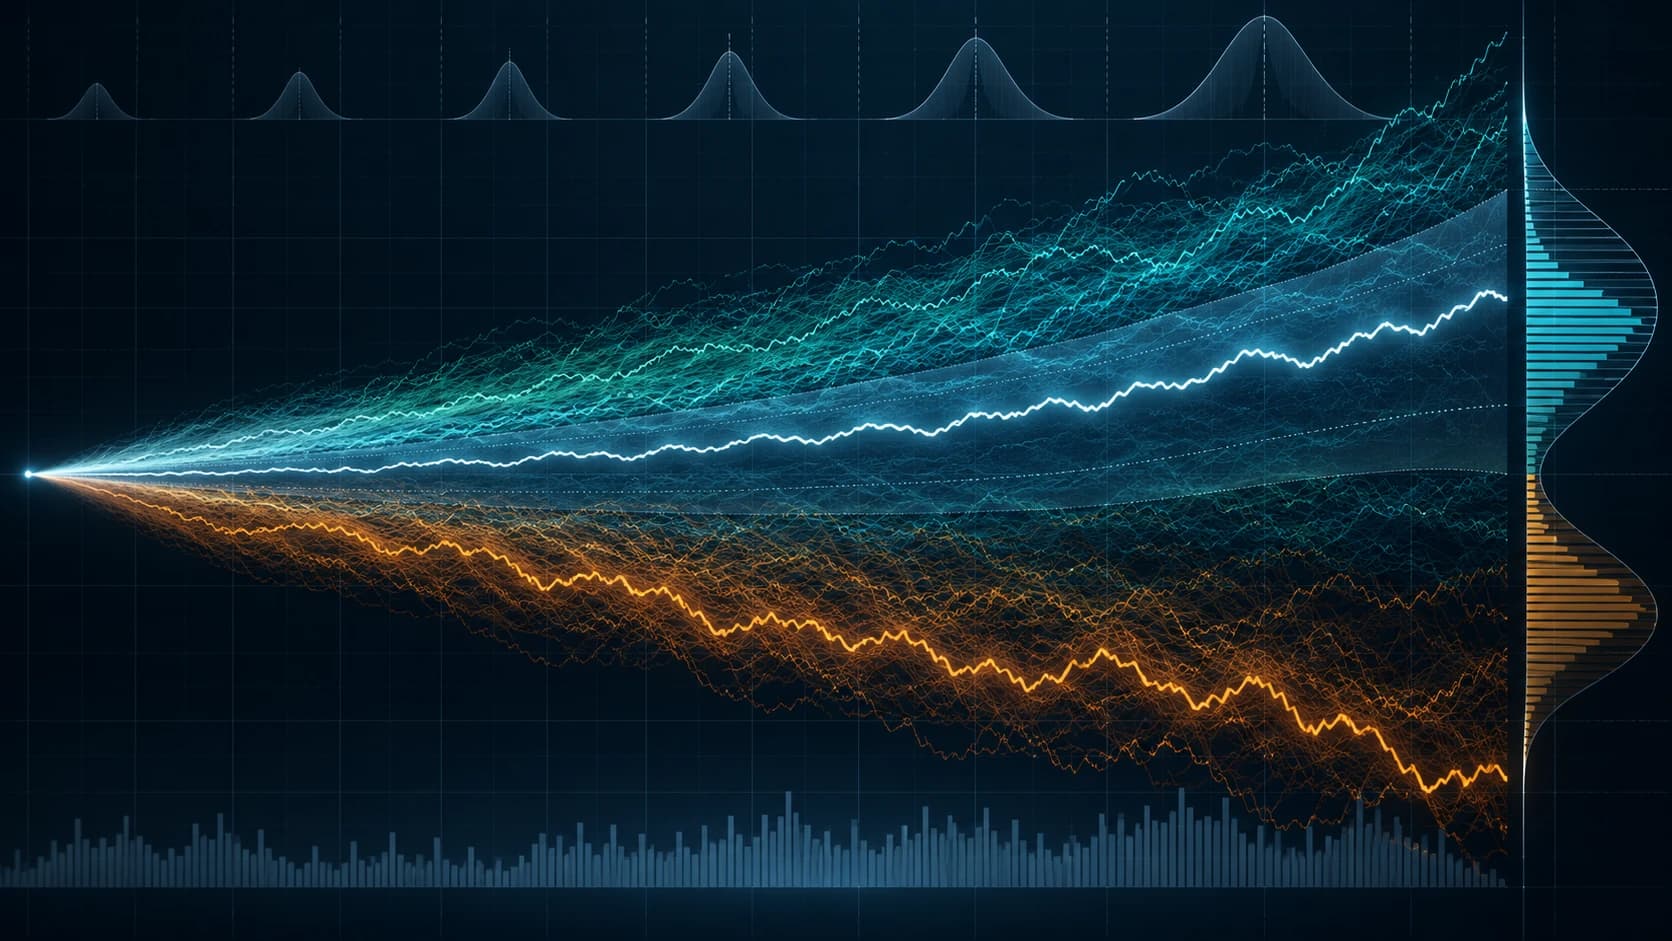
A backtest shows one historical sequence. The same trades arranged in a different order can produce a much deeper drawdown or a longer losing streak. Monte Carlo analysis creates many alternative paths from a set of assumptions so the trader can study a range of possible outcomes rather than one smooth equity curve.
It is a risk tool, not a prediction machine. Its conclusions are only as credible as the input data and simulation design.
1. Define the question
Useful questions include:
- What drawdown might occur over the next 100 trades?
- How long could a losing streak become?
- How often might the account fall below a chosen limit?
- Does a proposed risk per trade survive unfavourable sequencing?
Choose the number of trades, starting capital, sizing rule and failure threshold before running the simulation.
2. Choose a resampling method
The simplest method randomly rearranges historical trade results. This preserves the observed winners and losers but changes their order. Sampling with replacement allows a result to appear more than once and generates a wider set of sequences.
Independent resampling can be misleading when trades cluster by regime. A block method keeps groups of consecutive trades together, preserving some serial dependence. A parametric simulation draws from a fitted distribution, but the chosen distribution may underestimate extreme losses.
No method creates risks missing from the original assumptions. Add separate stress scenarios for gaps, liquidity failures or structural breaks.
3. Simulate the sizing rule accurately
Fixed monetary risk and percentage-of-equity risk behave differently. With percentage sizing, loss size shrinks after drawdown and grows after gains. Leverage, minimum contract size and portfolio overlap must also be reflected.
Run thousands of paths, then examine distributions rather than the best or average path. Useful outputs are median ending equity, fifth-percentile outcome, maximum-drawdown percentiles and losing-streak percentiles.
4. Avoid false precision
A 95th-percentile drawdown is not a guaranteed maximum. It means the model produced a smaller drawdown in 95% of simulated paths under its assumptions. Real markets can exceed the historical sample.
Confidence improves with more representative trades, but regime change remains possible. Use conservative stress additions and retest after material strategy changes.
Worked example
Assume a strategy has 200 historical results measured in R, with average expectancy of +0.18R. A trader resamples those trades 10,000 times into 100-trade sequences using a fixed 0.5% of current equity at risk per trade.
The hypothetical output is:
- Median maximum drawdown: 6%
- 90th-percentile maximum drawdown: 11%
- 95th-percentile longest losing streak: 12 trades
- 8% of paths finish below starting capital
The average edge is positive, yet some paths lose money and many are uncomfortable. If the trader doubles risk per trade, drawdowns do not simply feel twice as difficult; compounding and behaviour can make execution much harder.
These figures are illustrative. A real study must use the strategy's own clean, net-of-cost results and appropriate dependence assumptions.
Common mistakes
- Treating simulated percentiles as guaranteed boundaries.
- Using too few historical trades.
- Ignoring serial correlation and market regimes.
- Simulating gross results without costs or slippage.
- Leaving position sizing outside the model.
- Selecting a risk level only because the median path looks attractive.
Practical checklist
- What exact risk question should the simulation answer?
- Are trade results net of realistic costs?
- Is the sample representative of the intended strategy?
- Should trades be independent or resampled in blocks?
- Is the live position-sizing rule reproduced?
- Which drawdown and losing-streak percentiles matter?
- What stress losses are absent from the history?
- Would the plan remain executable on an adverse path?
The Money Man view
Monte Carlo analysis makes sequence risk visible. A strategy with positive expectancy can still deliver a painful path, and position size should be chosen for that possibility rather than the median outcome. We prefer conservative inputs, multiple resampling methods and explicit stress tests over a single precise-looking number.
Educational information only. This tutorial is AI-assisted and published by The Money Man. It is not personalised investment advice, a recommendation or a promise of returns. Simulations are hypothetical and trading can result in losses.