Portfolio Turnover: Trading Cost কীভাবে Edge কমায় তা মাপুন
সর্বশেষ সংরক্ষিত:
Executive Summary
- ✦Turnover formula লিখুন এবং traded notional, round trip ও holding time track করুন।
- ✦Cost stack-এ commission, spread, slippage, financing, market impact ও relevant tax রাখুন।
- ✦Gross expectancy ও net expectancy compare করে প্রতি trade-এর break-even edge calculate করুন।
- ✦Cost, delayed fill ও lower frequency stress করুন, এরপর realised execution-এর সঙ্গে modelled cost reconcile করুন।
Portfolio Turnover: Trading Cost কীভাবে Edge কমায় তা মাপুন
Learning objective
Portfolio turnover calculate, commission, spread ও slippage annual cost-এ convert এবং execution-এর পরে strategy positive expectancy রাখে কি না test করা শিখুন।
Turnover portfolio size-এর relative-এ strategy কত capital buy ও sell করে তা মাপে। High turnover automatically bad নয়, কিন্তু প্রতিটি replacement spread, commission, slippage, tax ও market impact দিয়ে gross return কমাতে পারে।
Step 1: consistent turnover measure করুন
Practical annual measure:
Turnover = total purchase বা total sale-এর lower value ÷ average portfolio value।
Platform ভিন্ন definition ব্যবহার করতে পারে, তাই formula record করুন। Trading strategy-তে round trip, average holding time ও traded notional-ও track করুন।
Step 2: cost stack তৈরি করুন
প্রতি entry ও exit-এ estimate করুন:
- commission ও exchange fee;
- entry ও exit-এর half-spread;
- decision price-এর against slippage;
- borrowing, funding বা financing cost;
- larger order-এর market impact;
- relevant tax।
Backtest-এ tested instrument, venue ও period-এর cost ব্যবহার করুন। Evidence ছাড়া current tight spread historical বা stressed data-তে apply করবেন না।
Worked example
Hypothetical £20,000 strategy বছরে capital ছয়বার turnover করে। তাই প্রায় £120,000 purchase ও £120,000 sale trade হয়।
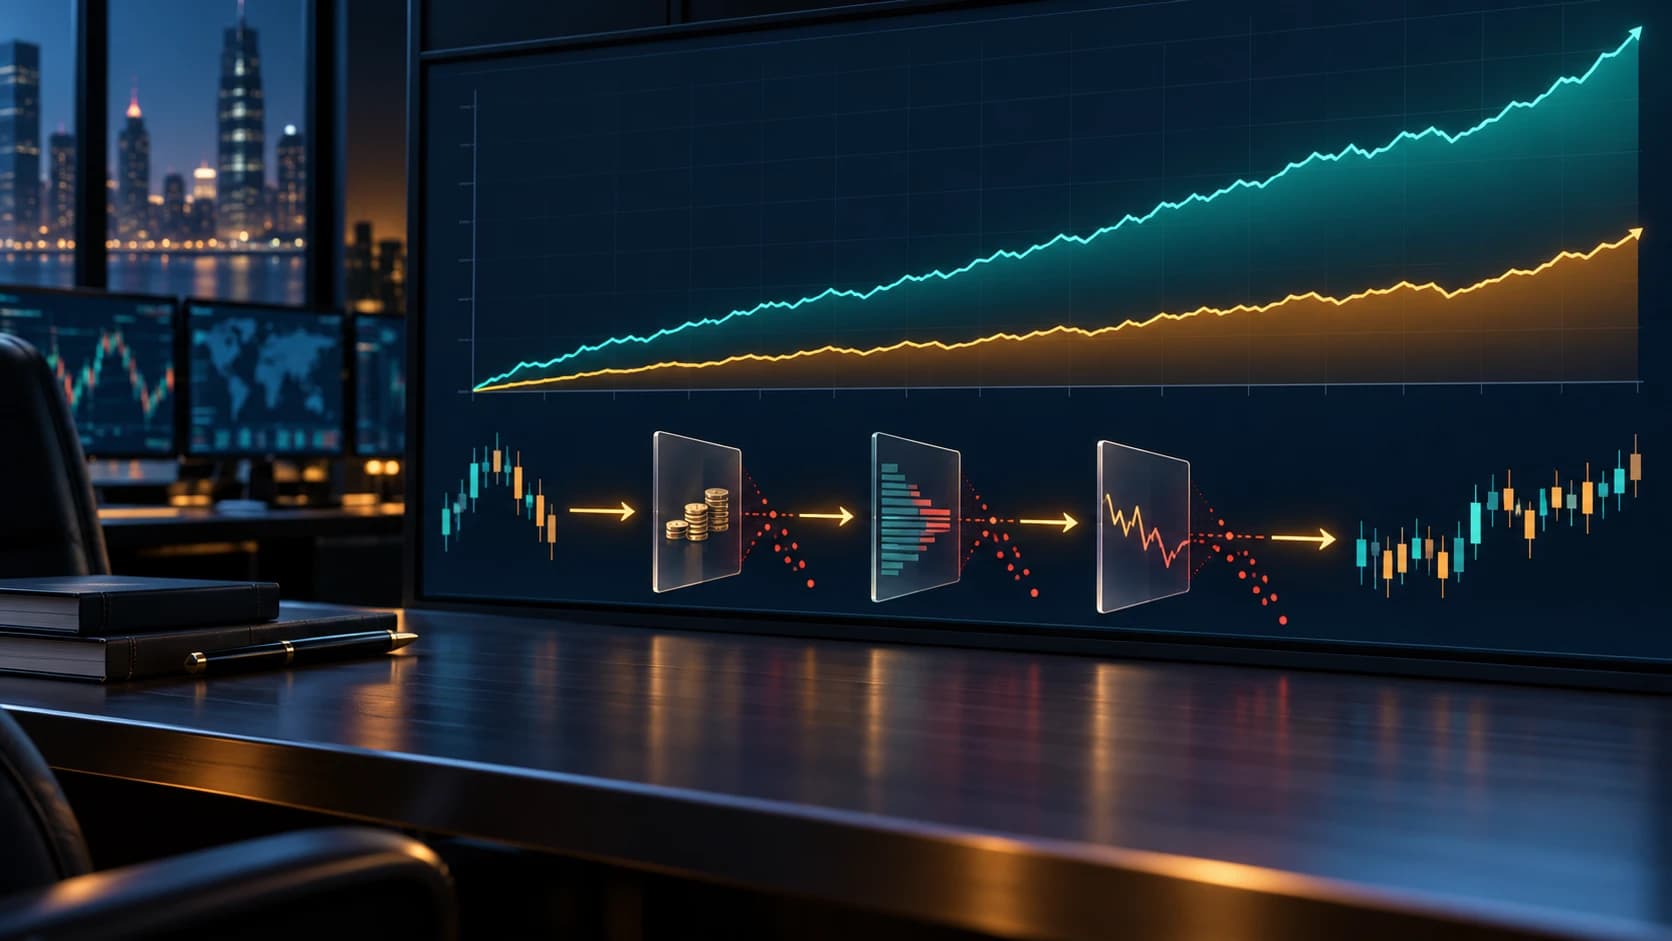
Average all-in round-trip cost 0.30% হলে estimated annual drag:
6 × 0.30% = 1.80%, £20,000-এ প্রায় £360।
Backtest gross return 7% হলে simplified net result tax-এর আগে 5.2%। Stressed spread ও slippage round-trip cost 0.70%-এ তুললে annual drag 4.2%, tax-এর আগে থাকে 2.8%।
এটি illustration, universal estimate নয়। Real cost size, venue, timing ও liquidity অনুযায়ী বদলায়।
Step 3: প্রতি trade-এর break-even edge calculate করুন
Average round-trip cost 0.30% হলে completed trade net profit contribute করার আগে signal-কে 0.30%-এর বেশি earn করতে হবে। Many tiny gross winner থাকা strategy high win rate নিয়েও fail করতে পারে।
Net expectancy = gross expectancy − commission − spread − slippage − financing।
Live monitoring-এ advertised minimum fee নয়, realised fill ব্যবহার করুন।
Step 4: turnover sensitivity test করুন
Result recalculate করুন:
- normal cost;
- normal-এর 1.5 times;
- normal-এর twice;
- lower trade frequency;
- delayed execution।
Small cost change পুরো profit remove করলে edge fragile। Turnover reduce সাহায্য করতে পারে, তবে filter strongest signal remove করছে কি না re-test করতে হবে।
Common mistakes
- Commission count করে spread ও slippage ignore করা।
- Historical backtest-এ today's liquidity ব্যবহার।
- Gross return-কে investable return ভাবা।
- Cost-এর আগে different-turnover strategy compare করা।
- Missed fill result বদলালেও limit order free ভাবা।
- Signal re-test ছাড়া frequency কমানো।
Practical checklist
- Turnover formula ও period লিখুন।
- Traded notional ও round trip track করুন।
- Instrument-specific cost stack বানান।
- Gross ও net expectancy compare করুন।
- Cost ও delayed fill stress করুন।
- Monthly actual fill-এর সঙ্গে modelled cost reconcile করুন।
- Unrealistically perfect execution-dependent result reject করুন।
এই tutorial The Money Man editorial workflow-এর অধীনে AI-assisted research ও writing দিয়ে তৈরি। এটি educational information, personalised investment advice নয়। Figure hypothetical এবং instrument ও venue অনুযায়ী cost materially বদলায়।