Trading Pre-Mortem: Find Failure Modes Before You Risk Capital
Last saved:
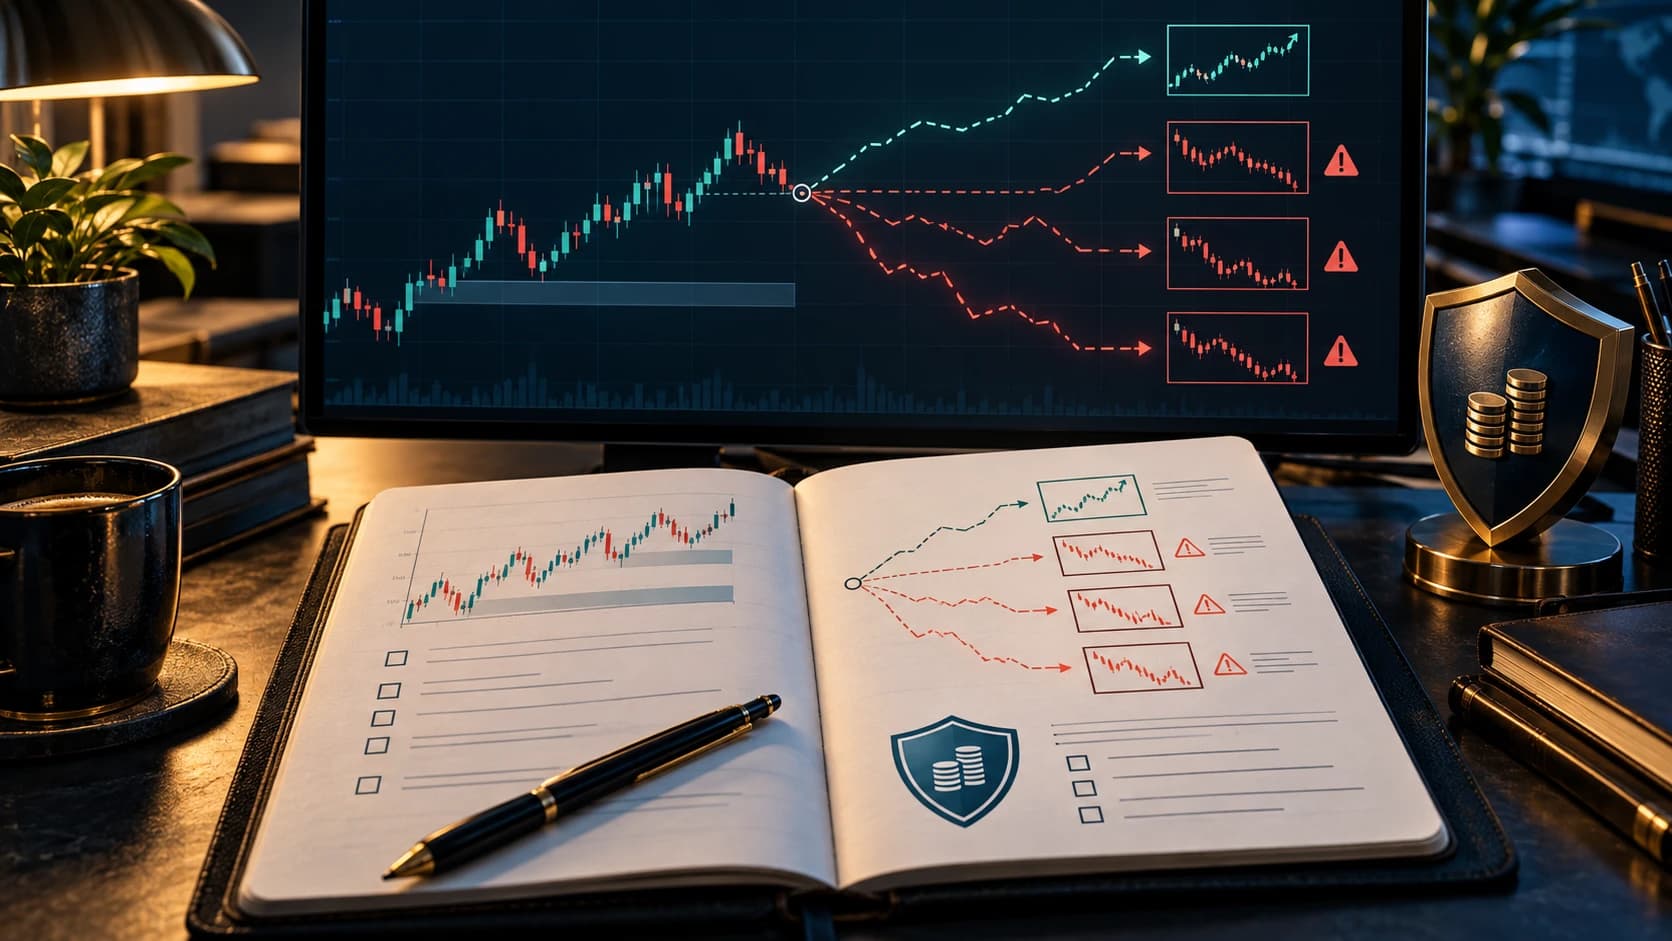
Executive Summary
- ✦Freeze the original thesis, trigger, invalidation, holding period and monetary risk before analysing failure.
- ✦Assume the trade lost more than planned, then identify thesis, market-structure, event, execution and behaviour failure modes.
- ✦Turn serious risks into observable warnings and controls; a stop cannot guarantee its trigger price during a gap.
- ✦Finish with an explicit keep, modify or skip decision and compare the pre-mortem with the post-trade review.
Trading Pre-Mortem: Find Failure Modes Before You Risk Capital
Learning objective
By the end of this guide, you will be able to run a short pre-mortem before a trade, identify failure modes that a normal bullish or bearish thesis can hide, convert those risks into observable warnings and decide whether to change the entry, reduce the size or skip the trade.
A trading plan usually asks: “Why should this setup work?” A pre-mortem asks a different question:
“Imagine the trade has already failed badly. What caused the failure?”
This is prospective hindsight—reasoning backwards from an imagined future outcome. Psychologist Gary Klein adapted the method into the project pre-mortem. In trading, it can make the risk section of a plan more concrete before money and ego are committed.
A pre-mortem is not a prediction that the trade will lose. It is a structured way to expose assumptions, gaps and execution risks while there is still time to change the plan.
Why an ordinary risk list may be too weak
When traders ask “what could go wrong?”, the answers often remain vague:
- the market could reverse;
- the news could disappoint;
- volatility could rise;
- the stop might be hit.
These statements are true but not operational. They do not specify the failure mechanism, the first observable warning or the action to take.
The pre-mortem makes failure a fact inside the exercise. Instead of defending the original thesis, the trader must explain the loss. That can reveal issues in five separate areas:
- Thesis risk: the economic or company assumption was wrong.
- Price risk: the chart trigger failed or the market structure changed.
- Event risk: new information arrived while the market was closed or illiquid.
- Execution risk: spread, slippage, queue position or a gap changed the planned loss.
- Process risk: the trader broke the plan, sized incorrectly or moved the invalidation.
Step 1: freeze the original plan
Write the plan before running the pre-mortem. At minimum include:
- instrument and timeframe;
- setup and entry trigger;
- thesis in one or two sentences;
- price or condition that invalidates the thesis;
- expected holding period;
- planned exit method;
- maximum planned monetary risk;
- known scheduled events during the holding period.
The word freeze matters. If the plan changes while risks are being identified, it becomes impossible to know which version is being assessed.
Keep facts separate from interpretation. “The index closed above the 20-day high” is an observation. “Institutional buyers will now drive a sustained trend” is an interpretation that can fail.
Step 2: assume the trade failed badly
Use a concrete failure statement:
“It is the end of the planned holding period. The trade lost twice the amount originally expected, and the thesis did not recover. Explain what happened.”
The phrase “twice the amount” forces the exercise beyond the obvious stop-loss answer. It raises questions about gaps, liquidity, incorrect contract value, leverage and delayed execution.
Generate reasons before judging them. If several people manage the publication or trading process, each person should first write independently. Early group discussion can anchor everyone to the first explanation.
Step 3: list failure modes by category
Use categories so the exercise does not stop at the market direction.
Thesis failure
- The catalyst was already priced in.
- Revenue rose but margins or guidance weakened.
- Higher oil helped producers but damaged the broader index.
- A correlation expected to hold broke during a new regime.
Market-structure failure
- The breakout closed above resistance but lacked participation.
- Price opened above the trigger and immediately returned into the range.
- The daily signal depended on a data timestamp or session boundary that was wrong.
- A futures roll or corporate action created a false chart move.
Event and gap failure
- A policy decision, earnings release or geopolitical headline arrived outside liquid hours.
- The market reopened beyond the stop.
- Related assets moved first while the chosen instrument was closed.
Execution failure
- The spread widened around the trigger.
- A limit order did not fill even though the displayed price was touched.
- A market order filled materially beyond the expected level.
- Position size used the wrong point value, currency conversion or contract multiplier.
Behavioural failure
- Fear of missing out caused an entry before confirmation.
- The stop was widened to avoid accepting a loss.
- A losing trade was averaged down without a pre-defined rule.
- A recent win increased size without a change in the strategy's evidence.
Step 4: separate invalidation from discomfort
Not every adverse move invalidates a trade. A position can move against the entry while the original thesis remains intact. Conversely, price can remain near entry even after the thesis has failed.
For each failure mode, write one of three labels:
- Thesis invalidation: evidence directly contradicts the reason for the trade.
- Risk escalation: probability or potential loss has worsened, but the thesis is not yet disproved.
- Normal noise: the move is within the setup's expected variability.
This prevents two common errors: exiting every uncomfortable move and holding every loss because the stop has not printed.
An invalidation should be observable. “The trade feels wrong” is not enough. Better examples include a daily close back inside the breakout range, guidance below a stated threshold, a volatility measure exceeding the level used for sizing, or a scheduled release that materially changes the thesis.
Step 5: convert each serious risk into a control
A risk list has little value unless it changes a decision. For each high-impact failure mode, define:
| Failure mode | Early warning | Control |
|---|---|---|
| Opening gap beyond stop | Major event before next liquid session | Reduce exposure, delay entry or use defined-risk structure |
| False breakout | Close returns inside prior range | Require closing confirmation or exit on pre-defined failure |
| Spread expansion | Current spread exceeds tested assumption | Use a limit, reduce size or do not trade |
| Wrong contract value | Platform risk differs from manual calculation | Reconcile size before sending order |
| Thesis drift | New rationale appears after entry | Save original thesis and reject unplanned justifications |
Controls are conditional choices, not guarantees. A stop order cannot guarantee its trigger price during a gap, and a limit order can avoid a bad price by providing no fill at all.
Worked example: a hypothetical index breakout
Assume a trader is considering a long daily-timeframe trade in a hypothetical index:
- breakout trigger: 8,050;
- planned entry: 8,060 after a daily close confirms;
- invalidation: 7,980;
- target reference: 8,220;
- distance from entry to invalidation: 80 points;
- account used in the example: £20,000;
- example risk budget: 0.5%, or £100.
Ignoring costs, the size that maps £100 to an 80-point move is:
£100 ÷ 80 = £1.25 per point.
The normal plan appears to risk £100. Now run the pre-mortem:
“The trade lost about £200 even though the plan allowed £100. What happened?”
Possible explanations:
- A weekend policy headline caused the index to open at 7,900, 160 points below the entry.
- The breakout was created by a thin closing auction and reversed at the next open.
- The spread widened from 2 points to 12 points when the stop triggered.
- The instrument was priced in another currency and the conversion was omitted.
- The trader added a second position during the decline without updating total risk.
The first failure mode is material. A stop near 7,980 would not guarantee an exit there if the market reopened at 7,900. At £1.25 per point, the 160-point gap would imply roughly £200 before additional costs.
The control could be to avoid holding through the event, wait until after the event, reduce exposure, or choose a genuinely defined-risk instrument after understanding its premium, liquidity and expiry behaviour. The correct choice depends on the strategy and does not eliminate risk. The important point is that the pre-mortem revealed that planned stop distance and maximum possible loss were not the same thing.
Suppose the trader halves the size to £0.625 per point solely for this event-risk example. The same 160-point gap would then produce about £100 of price loss before costs. That does not make the trade safe; a larger gap remains possible. It shows how a failure scenario can inform size.
Step 6: rank risks instead of treating them equally
Score each failure mode using simple categories:
- likelihood: low, medium or high;
- impact: manageable, serious or strategy-threatening;
- detectability: early, late or only after the loss.
A low-likelihood but strategy-threatening event may still require action if it cannot be detected early. A high-likelihood but small cost may belong in normal slippage assumptions.
Avoid false precision. Assigning 17% probability to an event without evidence does not make the analysis more rigorous. The purpose is to prioritise controls, not decorate the checklist with numbers.
Step 7: decide—keep, modify or skip
Finish the pre-mortem with one explicit decision:
- Keep: identified risks are already within the tested plan.
- Modify: change entry, confirmation, size, instrument, timing or exit rule.
- Skip: the risk cannot be bounded well enough for the strategy.
Write why. “Skip because risk is high” is vague. “Skip because earnings occur before the next liquid session and the strategy has no tested gap model” is reviewable.
Do not keep adding controls until every possible loss appears removed. Complex controls can create new execution failures and may convert a simple edge into an untestable process.
Step 8: compare the pre-mortem with the post-trade review
After the trade closes, ask:
- Did any listed failure mode occur?
- Was there an important failure mode the exercise missed?
- Did an early warning appear in time to act?
- Was the control followed?
- Did the control reduce loss or unnecessarily remove a valid trade?
Update the checklist from repeated evidence, not from one dramatic outcome. A pre-mortem should improve the process; it should not become a tool for explaining every loss after the fact.
Common mistakes
Turning the exercise into bearish analysis
The purpose is to find process and risk failures, including failures that can hurt a short position. It is not a reason to predict that every market will fall.
Listing only price risk
Some of the largest deviations from planned loss come from sizing, currency, contract specifications, liquidity and gaps.
Writing controls after entry
A control invented under pressure is vulnerable to emotion and hindsight. Define it before committing risk.
Confusing a stop with guaranteed loss
A stop is an execution instruction after its trigger; the fill can differ, especially during gaps or illiquid markets.
Making the checklist too long
If every trade requires a 50-item form, the process will be abandoned or completed mechanically. Keep a short core list and add setup-specific questions.
Using the pre-mortem to justify tiny or zero risk everywhere
Risk cannot be eliminated from trading. The exercise should reveal whether risk is understood, priced and consistent with the tested process.
Five-minute pre-trade checklist
- Is the original thesis written in observable terms?
- What exact evidence invalidates it?
- Imagine the loss was twice the plan: what caused the difference?
- Could the market gap beyond the stop?
- Are contract value, currency and total portfolio exposure reconciled?
- What happens if the order does not fill or fills late?
- Which scheduled events occur during the holding period?
- What is the earliest warning for each serious failure mode?
- Does each material risk have a control or a reason to accept it?
- Is the final decision keep, modify or skip?
Sources
The exercise is adapted from Gary Klein's Performing a Project Premortem, published by Harvard Business Review in 2007. Its prospective-hindsight foundation is discussed in Mitchell, Russo and Pennington's 1989 paper, Back to the Future: Temporal Perspective in the Explanation of Events. The US Agency for Healthcare Research and Quality also documents the pre-mortem as a structured way to identify and mitigate barriers before implementation.
This tutorial was prepared with AI-assisted research and writing under The Money Man editorial workflow. It is educational information, not personalised investment advice. The worked example is hypothetical, percentage risk is illustrative and no checklist can guarantee a trading outcome.