TWAP, VWAP and Participation Algorithms: Plan Large-Order Execution
Last saved:
Executive Summary
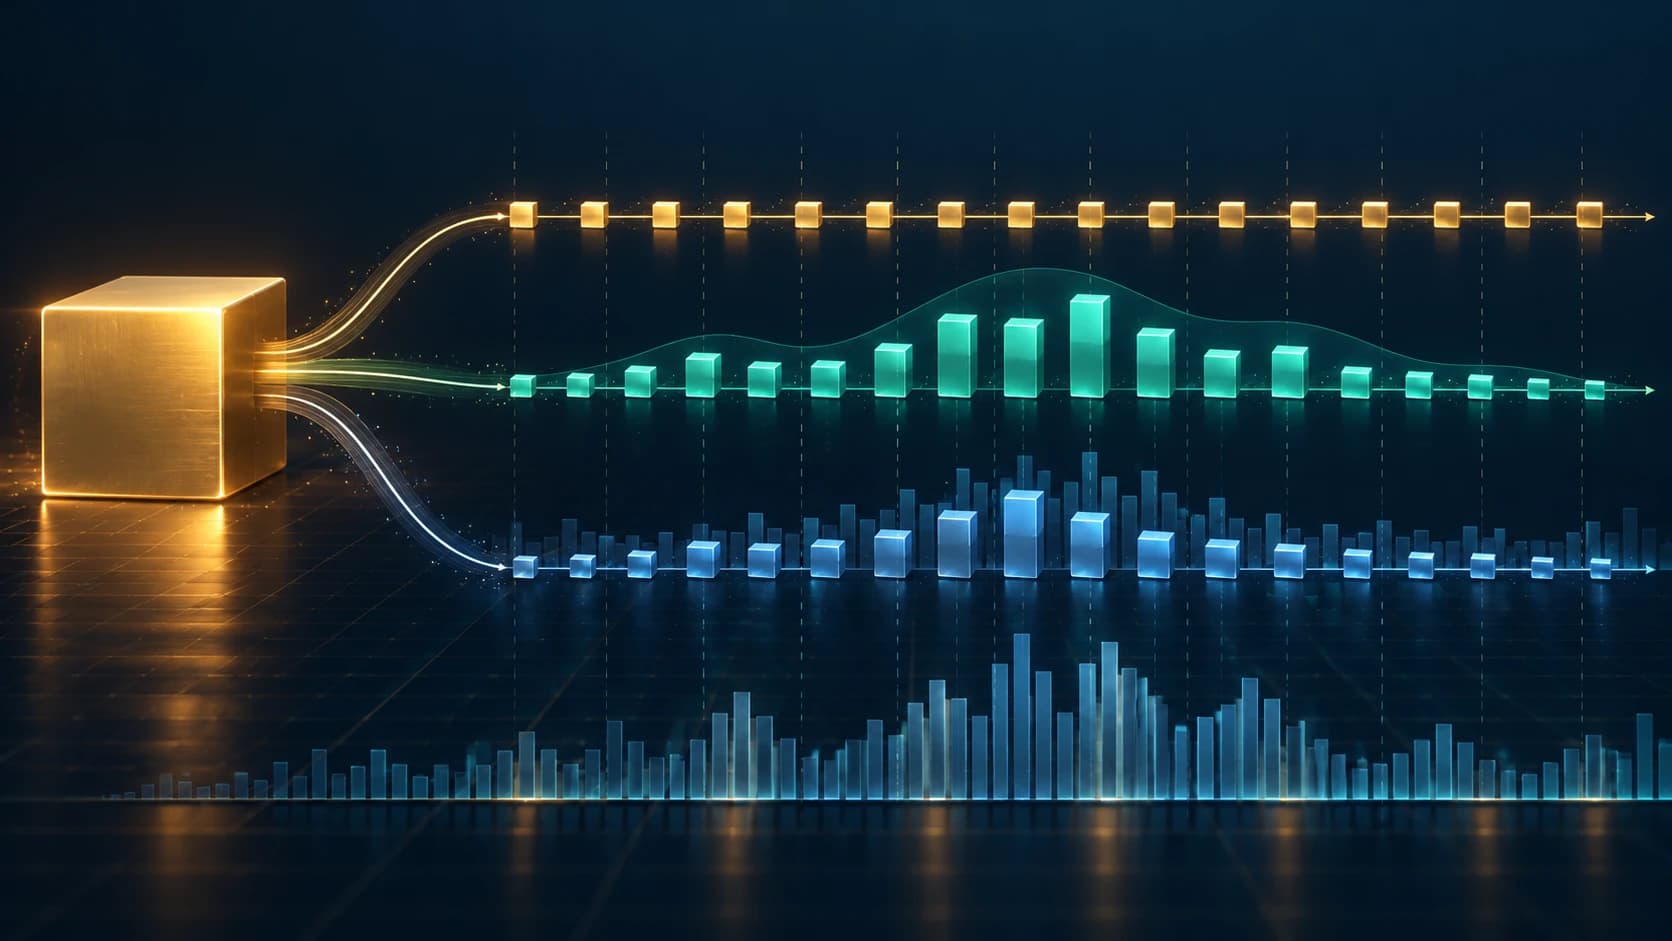
- ✦TWAP releases quantity at a relatively constant rate, VWAP follows a forecast volume curve and POV scales with realised market volume.
- ✦A benchmark evaluates fills while a strategy places child orders; sharing a name does not guarantee benchmark performance.
- ✦Slower execution may reduce immediate impact but increases timing and completion risk.
- ✦Define price, participation, auction, pause and residual-order controls before releasing the parent order.
TWAP, VWAP and Participation Algorithms: Plan Large-Order Execution
Learning objective
By the end of this tutorial, you should be able to explain how TWAP, VWAP and percentage-of-volume schedules split a parent order, identify the benchmark each approach emphasises and select risk controls without assuming that an algorithm guarantees a good fill.
Why split an order?
An order can be large relative to the shares available at the best bid or offer. Sending the whole quantity immediately may sweep several price levels, reveal urgency and move the market. An execution algorithm can divide the parent order into smaller child orders released over time.
This changes the trade-off rather than removing it. Slower execution may reduce immediate market impact but increases the risk that the market moves away before the order is complete. Faster execution reduces completion risk but can increase spread cost and price impact.
1. Three common schedules
TWAP: time-weighted schedule
TWAP aims to execute at a relatively constant rate through a chosen interval. Nasdaq describes TWAP as executing the desired quantity at a constant rate.
It is simple and predictable. It does not adapt naturally to a market where volume is much heavier at the open and close than at midday.
VWAP: historical volume-shaped schedule
VWAP allocates more of the order to periods that are expected to have more market volume. Nasdaq's execution guide says the schedule uses historical market, sector and stock volume patterns to create a trading trajectory intended to track volume-weighted average price.
The schedule can fit the normal liquidity curve, but it relies on a volume forecast. An earnings announcement, index rebalance or news shock can make today's pattern very different from history.
Percentage of volume, or POV
A participation algorithm tries to represent a chosen fraction of actual market volume. If the target is 10%, the strategy attempts to trade roughly one share for every ten shares traded in the market, subject to limits and available liquidity.
POV adapts to realised volume. Completion time becomes uncertain: a quiet market slows the order, while a sudden volume spike can cause the algorithm to trade quickly.
2. Worked example
Assume a trader must buy 12,000 shares over six hourly buckets. This is hypothetical and ignores lot size, spread, fees and partial fills.
TWAP schedule
An even split is:
12,000 ÷ 6 = 2,000 shares per hour
The target schedule is 2,000 shares in every bucket, even if market volume changes.
VWAP schedule
Suppose the forecast volume profile is:
| Hour | Forecast share of daily volume | Target child quantity |
|---|---|---|
| 1 | 15% | 1,800 |
| 2 | 10% | 1,200 |
| 3 | 15% | 1,800 |
| 4 | 20% | 2,400 |
| 5 | 25% | 3,000 |
| 6 | 15% | 1,800 |
The parent order is still 12,000 shares, but the schedule trades more during forecast high-volume periods.
10% participation schedule
Assume realised market volume by hour is 8,000, 12,000, 18,000, 15,000, 30,000 and 37,000 shares. Ten per cent participation implies child quantities of 800, 1,200, 1,800, 1,500, 3,000 and 3,700 shares. These add to 12,000, but another day's volume could leave the order incomplete or complete it earlier.
This example describes scheduling logic, not expected performance. Actual algorithms use order-book state, venue selection, price limits, minimum fill sizes and other controls.
3. A benchmark is not the same as a strategy
TWAP and VWAP can refer to market-price benchmarks as well as algorithms designed to trade around those benchmarks.
- A benchmark is the reference used to evaluate fills.
- A strategy is the rule used to place child orders.
An algorithm labelled VWAP can finish better or worse than the market's realised VWAP. A favourable comparison can also reflect market direction rather than skill. For a buy order in a steadily falling market, waiting may look good against arrival price; in a steadily rising market, the same patience can look costly.
Review implementation shortfall to compare the executed portfolio with the decision price and include delay, missed quantity and fees.
4. Key execution risks
Market impact
Child orders can still consume liquidity and move price, especially when the participation rate is high relative to normal depth.
Timing risk
The market can move adversely while the unexecuted balance remains exposed.
Information leakage
A repetitive size and interval can make the schedule predictable. Other participants may infer the parent order.
Completion risk
Passive limits or a low participation rate may leave part of the order unfilled by the deadline.
Volume forecast risk
VWAP schedules can fall behind or get ahead when realised volume differs from the historical curve.
Venue and routing risk
Quotes represent limited size, execution is not instantaneous and routing affects fill price and likelihood. The SEC notes that investors may not receive the price displayed when their order enters the market.
Auction risk
Opening and closing auctions may concentrate liquidity but can also create a large benchmark-sensitive fill. Confirm whether the selected algorithm participates in auctions; Nasdaq's VWAP documentation notes participation may require explicit instruction.
5. Choosing among the approaches
TWAP can be useful when the trader wants a predictable pace and the expected volume curve is uncertain or relatively flat. It may be a poor fit when liquidity varies sharply through the session.
VWAP can be useful when the benchmark matters and the instrument has a stable, well-estimated intraday volume pattern. It becomes less reliable on event days.
POV can be useful when the order should scale with realised liquidity. It cannot guarantee a finish time and may accelerate during noisy volume spikes.
No label determines suitability by itself. Order urgency, size versus average volume, spread, volatility, news, deadline, benchmark and risk limits all matter.
6. Controls to define before release
- Start and end time: the interval in which trading is allowed.
- Price limit: the worst acceptable price, recognising that a strict limit can prevent completion.
- Maximum participation: a ceiling on the share of market volume.
- Minimum and maximum child size: to avoid uneconomic or conspicuous orders.
- Auction instruction: include or exclude opening and closing auctions.
- Catch-up rule: whether the algorithm becomes more aggressive if it falls behind schedule.
- Pause conditions: volatility halt, news, spread widening or data failure.
- Residual handling: what happens to the unfilled balance near the deadline.
These controls should be tested against the instrument's liquidity. A limit can protect price while increasing non-completion risk.
7. Post-trade review
Record:
- Decision and arrival price
- Start and finish time
- Parent and executed quantity
- Child fills, venues and fees
- Realised spread and slippage where available
- Market TWAP or VWAP over the correct interval
- Percentage of market volume
- Unfilled or cancelled quantity
- Price move before, during and after execution
Separate market movement from execution cost. A profitable trade can be poorly executed, and a losing trade can be efficiently executed relative to the available market.
Common mistakes
- Treating VWAP as a directional buy or sell signal. See our VWAP guide.
- Assuming equal child sizes mean equal market impact.
- Selecting TWAP merely because the name matches the reporting benchmark.
- Using historical VWAP patterns on an event day without adjustment.
- Setting a POV rate without estimating completion time.
- Omitting a price limit or residual-order rule.
- Comparing fills with a benchmark from the wrong time window.
- Ignoring fees, spread, opportunity cost and unfilled quantity.
Checklist
- Parent quantity and deadline defined?
- Size compared with normal market volume and depth?
- Benchmark and strategy distinguished?
- Volume forecast or participation assumption documented?
- Price, participation and pause limits set?
- Auction and residual instructions specified?
- All fills and fees captured?
- Post-trade review includes missed quantity and market direction?
Sources
- Nasdaq Nordic: Execution algorithms
- Nasdaq: Execution Algorithms User Guide
- SEC: What every investor should know about trade execution
- FINRA: Understanding the online trade lifecycle
This tutorial was prepared with AI-assisted research and writing under The Money Man editorial workflow. It is educational information, not personalised investment advice, broker instructions or a recommendation to use a particular execution algorithm. The worked order is hypothetical.